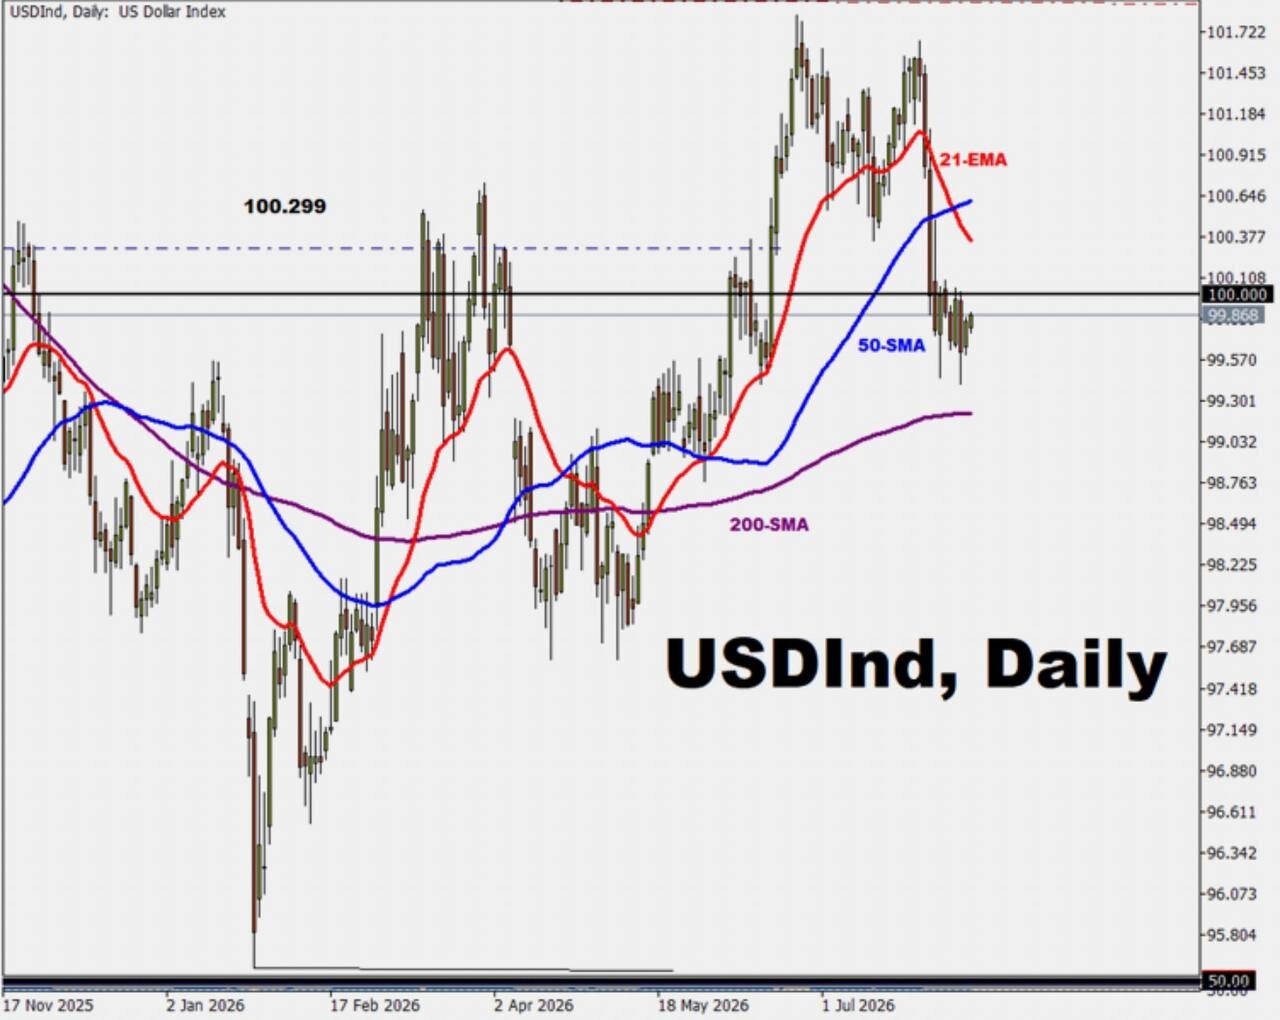
USDInd rebounded to 99.81 this week after touching a two-month low, but the outlook remains fragile. A weak US jobs report reduced expectations for a September Fed rate hike, with market pricing falling from around 64% to 46%.
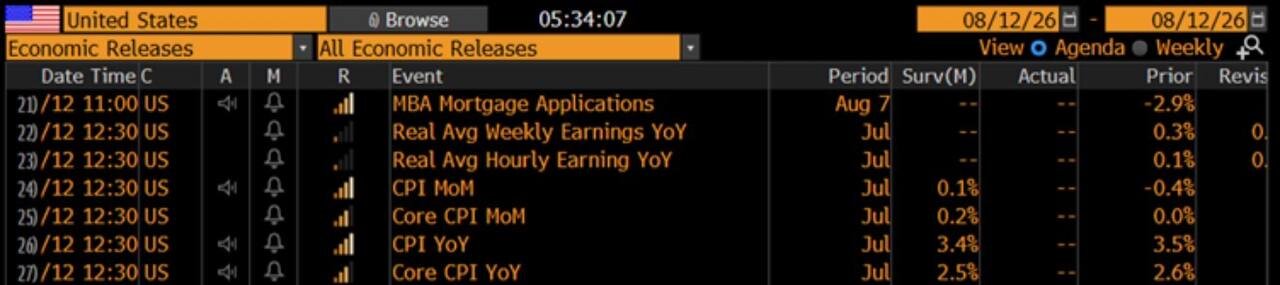
The next major catalyst is US inflation. July CPI is expected to show further easing in price pressures:
• Core CPI is forecast to slow to 2.5% year-on-year from 2.6%, the lowest since March 2021.
• Headline CPI is expected at 3.4% year-on-year, down from 3.5%, partly reflecting lower gasoline prices in July.
• Bloomberg projects core inflation to ease further toward 2.2%–2.3% in August and September.
• If inflation continues to cool, core PCE could move closer to the Fed’s 2% target, further reducing the case for another rate hike.
• Bloomberg Economics expects the Fed to keep rates unchanged in September.
What could move USDInd:
A softer-than-expected CPI reading could put renewed pressure on the dollar by weakening expectations for further Fed tightening. A stronger core inflation print would revive the higher-for-longer narrative and could trigger another USD rebound.
When: Wednesday, 12 August, 13:30 GMT